Diffusion & Innovation Systems
From S-curve adoption to running an Innovation Management System — and the four assignments that go with it
What is innovation diffusion?
Definition. Diffusion is the process by which an innovation is communicated through certain channels, over time, among members of a social system. It is distinct from invention (creating something new) and innovation (bringing it to practical use) — diffusion is what happens after that, as the market actually adopts it.
Three phases, one curve
The S-curve in Vietnam: smartphone adoption
Phase 1: Emergence (2008–2010)
First smartphones (original iPhone, early Android HTC) appear in Vietnam. Devices are very expensive, 3G is in its infancy, most people still use "brick phones."
Phase 2: Growth (2012–2018)
Affordable Xiaomi, Oppo, Samsung A-series phones flood the market. Nationwide 3G/4G plus Zalo, Facebook, Grab make a smartphone a necessity for nearly everyone.
Phase 3: Maturity (2020–present)
Almost every adult owns a smartphone. Few first-time buyers remain; competition shifts to the high end, or to the next upgrade cycle.
Five adopter categories
5 attributes that drive the rate of adoption
1. Relative Advantage
Is it significantly better than existing solutions — on price, speed, convenience?
2. Compatibility
Does it fit existing values, habits and technical infrastructure?
3. Complexity
Is it hard to understand or use? Higher complexity → slower adoption.
4. Trialability
Can users experiment with it on a limited or free basis first?
5. Observability
Are the results and benefits easily visible to others?
The core process: Search → Select → Implement → Capture Value
The "4Ps" of innovation
One company, four kinds of innovation
Product
1964 wooden first mouse → 1970s–80s Xerox/Apple models → 1980s–2000 mechanical → 2000s–present wireless.
Process
Robotic welding and moving assembly lines changed how cars are built, not what a car is.
Position
Launched as a convenient wearable, later repositioned primarily as a health- and fitness-tracking device for a different buyer.
Paradigm
From mailing DVDs to a streaming subscription business — a new business model, not just a new product.
No firm innovates alone
Firm-Level (Internal)
- Strategy: clear intent, supportive leadership
- Flexible, agile structure
- Culture that rewards creativity
- Learning from success and failure
Inter-Organizational
- Open innovation: internal + external sources
- Supply chains & alliances, university partnerships
- Ecosystems & platforms co-creating value
National & Regional
- Institutional setup: universities, public R&D
- IP protection, standards, policy
- Venture capital, tax incentives
- Local cluster dynamics
Why manage innovation at all?
The necessity
- Align innovation with strategic direction, resources, metrics
- Keep strategy flexible as opportunities change
- Balance exploiting today’s process with exploring new ones
- Remove barriers and mindsets that stifle initiative
- Ground innovation in real market and customer needs
The roles it plays
- Focuses the enterprise on its most critical innovation activities
- Lets top management define a vision and allocate resources
- Builds a shared, organization-wide awareness of innovation work
- Surfaces bottlenecks through assessment
- Integrates with the firm’s other management systems
The fundamental elements, and 7 evaluation principles
4 fundamental elements
- Context of the organization: internal/external issues relevant to objectives
- Leadership: vision, strategy, policy, roles
- Planning: activities that address opportunities and risks
- Support: people, finance, tools, IP strategy
7 evaluation principles
- Increasing value for the business
- Challenging goals & strategies
- Mobilizing business development
- Focusing on the future
- Relevance to context, best practice
- Flexibility & comprehensiveness
- Effectiveness & reliability
A global standard, built by 40+ countries
Four tasks attached to this lecture, numbered 1–3 and 5
| # | Type | What's required |
|---|---|---|
| 1 | Analysis (in-class) | Analyze the role of innovation management in enterprises, with illustrative examples. |
| 2 | Group activity, 30–40 min | Pick a real product (EV, air fryer, GenAI tool, QR payments). Evaluate it on the 5 attributes, place it on the S-curve / adopter spectrum, propose 1–2 strategies to cross the chasm into the Early Majority. |
| 3 | Homework (~300 words) | Reflect on why a technologically advanced product failed during its diffusion phase. |
| 5 | Presentation (graded) | Full "Analysis of an Innovation" deck — 5-part structure, worked example provided (Selex Motors). |
"Analysis of an Innovation" — 5-part structure
| Part | Covers |
|---|---|
| 1. Introduction | Title, problem statement, objective — why this innovation was chosen |
| 2. Overview | Product/model description, type of innovation (Product/Process/Position/Paradigm), level (Disruptive/Incremental/Radical), target users |
| 3. Core Analysis | Value proposition, key success factors, market adoption evidence |
| 4. Impact & Challenges | Positive impact, risks/barriers, full SWOT analysis |
| 5. Conclusion | Summary, key lessons applicable elsewhere, Q&A |
Selex Motors: EV ecosystem & battery swapping
The problem
Grab/Be/ShopeeFood drivers lose 3–8 hours a day charging EVs; gasoline price swings raise costs further.
The solution
Selex Motors (founded 2018): smart EVs + standardized batteries + automated "2-minute battery swap" stations, Battery-as-a-Service.
Type & level
Product innovation (EV + battery) combined with Business Model innovation (BaaS). Disruptive — replaces passive charging and gasoline refueling habits.
Evidence of adoption
Hundreds of swap stations in Hanoi & HCMC; >90% driver satisfaction; drivers report 20–30% higher daily income from eliminated downtime.
Completing Exercises 1, 2, 3 & 5 — four different ways of thinking, one example each
"Analyze the role of innovation management": the 5 official roles
| Role of innovation management | What it means in practice | Evidence from Grab (detailed next) |
|---|---|---|
| 1. Creating & sustaining competitive advantage | Not a one-time edge — an edge that keeps renewing itself against copycats | EXP: hundreds of A/B tests a month keep fine-tuning matching/pricing on the same driver network — why no SEA rival, including Uber, could out-execute Grab on its own turf |
| 2. Integrating technology, market & organization | Tech alone, or demand alone, isn’t innovation — it has to be assembled into one working system | The super-app flywheel: EXP (tech) + 47M monthly users (market) + licenses across 8 countries (organization) fused into one loop, each side feeding the others |
| 3. Transforming ideas into real value | An idea is worthless until it is actually captured as revenue, not just launched | GrabMaps: built in 2022 purely to serve Grab’s own drivers, later sold B2B. And 14 years from MyTeksi to Grab’s first-ever net profit, $200M in FY2025 |
| 4. Building & optimizing dynamic capabilities | The capability to keep re-tuning the business model as the market itself matures | Incentive spend deliberately cut from 13.3% of GMV (2022) to ≈10% (2024) while users kept growing 32.7M→47.2M — optimized, not accidental |
| 5. Managing risk & optimizing resources | Scaling fast without scaling the firm’s exposure to fraud, regulation, or bad bets | GrabDefense protected 4.5B transactions from fraud in 2024; years spent securing financial licenses market by market before launching GrabFin/GXS Bank |
Grab: resources only some founders start with
Family capital & domain expertise — verified
- Grandfather Tan Yuet Foh co-founded Tan Chong Motor in 1957, Malaysia’s Nissan distributor; father Tan Heng Chew is its president
- Anthony Tan worked as head of supply chain and marketing at Tan Chong before leaving in 2012 — real logistics-network experience, not a random MBA idea
- Family motto per his own CNBC account: "you can sleep soundly when you are dead" — documented innovation culture (IMS principle 4) instilled before day one
- His own retelling adds 5 years of hands-on factory work, welding and assembling seats — a self-reported detail, not independently verified beyond his interviews
Seed capital & the Select decision — verified
- 2011: Harvard competition, 2nd place, $25k — judges said Malaysia alone was too small, think Southeast Asia — that comment became the actual regional strategy
- His mother funded his first money ("I don’t understand, but I love you, so here is some money"); he added his own savings
- MyTeksi launched Kuala Lumpur, June 2012; first institutional round, $2M+ from Vertex Ventures, June 2013
- This is the Select stage of Search→Select→Implement→Capture Value, forced by outside feedback, not planned in advance
Grab: the three systems behind $22.1B in GMV
EXP: the Search→Capture loop, running monthly
- Internal A/B-testing system: drivers/riders randomly split into groups, old vs. new matching or pricing logic compared on real outcomes
- Hundreds of experiments run every month — fares and matching are continuously re-optimized on the same driver network, no new product launch needed
- This is Capture Value treated as a repeatable monthly process, not a one-time launch event
The flywheel, proven in Grab’s own filed numbers
- Incentive spend fell from 13.3% of GMV (2022) → 9.9% (2023) → ≈10% (2024), while monthly users grew 32.7M → 41.3M → 47.2M
- FY2025 (filed Feb 2026): first-ever full-year net profit, $200M, on $3.37B revenue (+20%) and $22.1B GMV (+21%) — after losses of $485M (2023) and $158M (2024)
- GrabMaps: built in 2022 purely to route Grab’s own drivers through motorbike alleys standard maps miss — then sold B2B once it worked. An innovation nobody set out to sell.
Grab: the same discipline, seen from the driver’s seat
Drivers organize
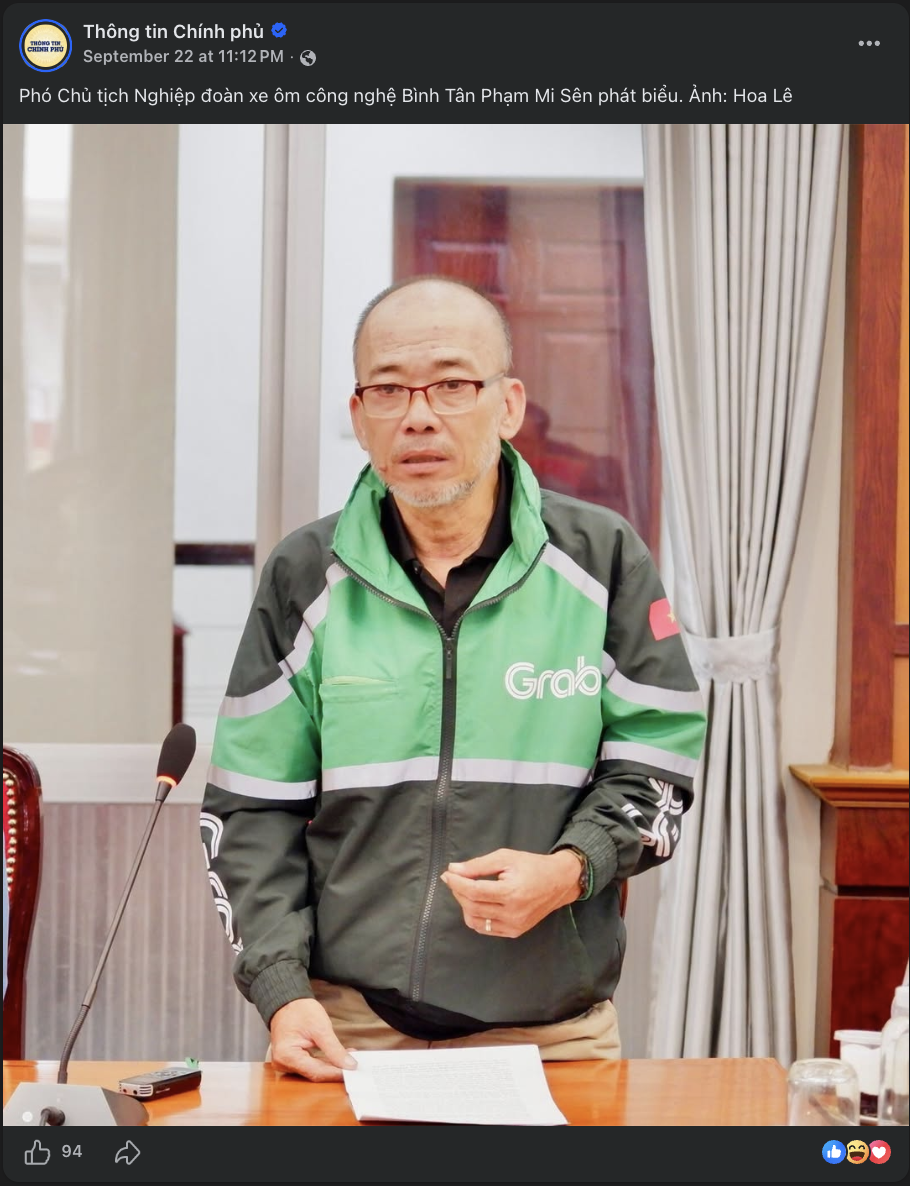
Sept 22, 2026: Phạm Mi Sên, Vice Chair of the Bình Tân Tech Motorbike-Taxi Union, speaks at an official meeting — the gig drivers Grab once empowered are now organized labor with a seat at the table.
Thông tin Chính phủ, official Facebook page. Photo: Hoa Lê.Regulators review fees
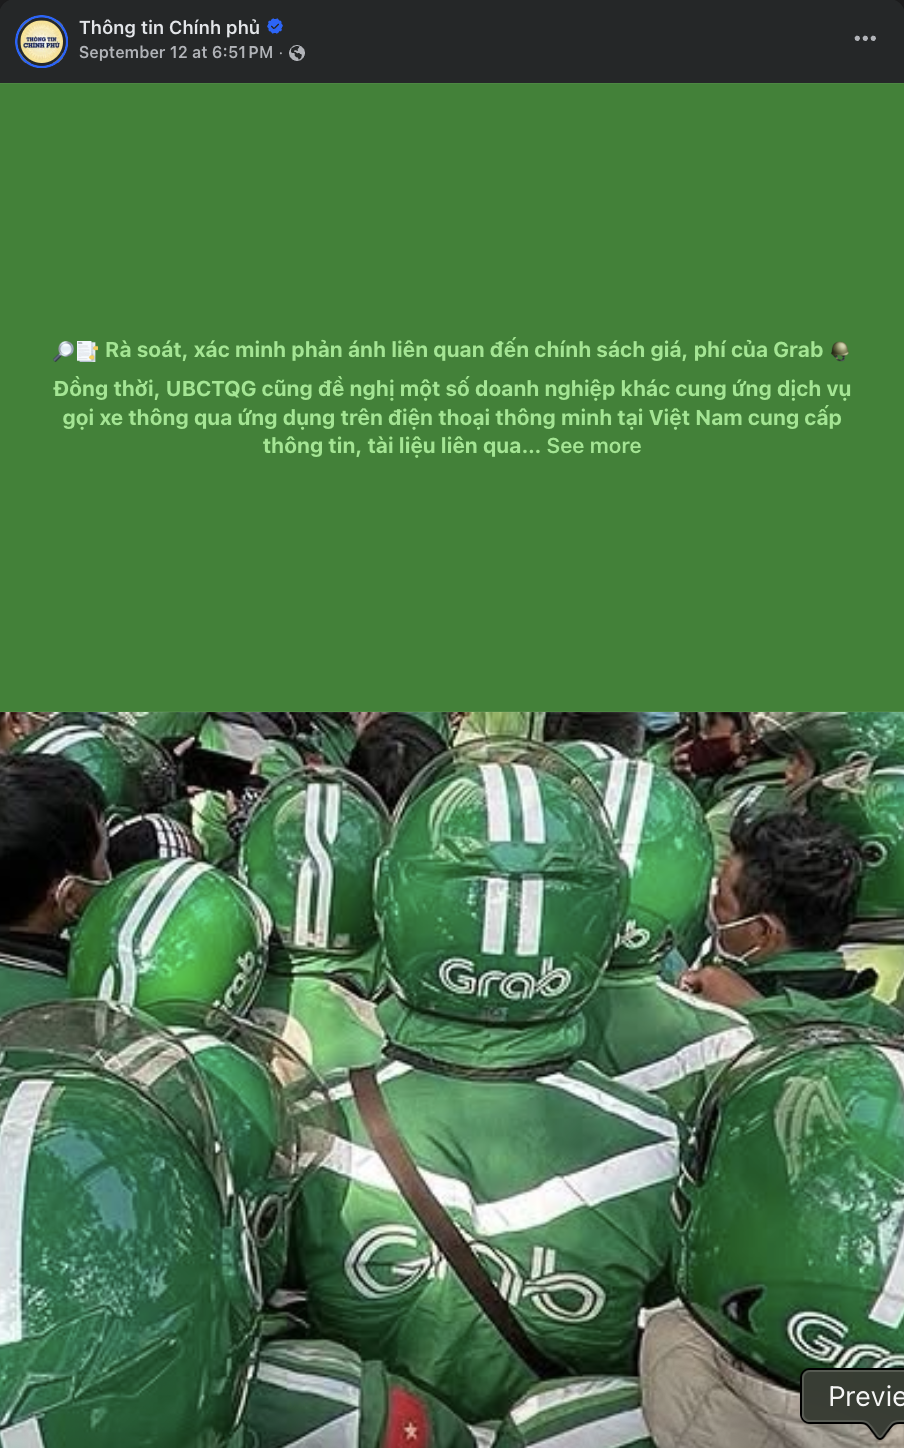
Sept 12, 2026: Vietnam’s National Competition Commission (UBCTQG) opens a review of Grab’s pricing and fee policy, and asks other ride-hailing apps for related information.
Thông tin Chính phủ, official Facebook page.Why this is an IMS problem, not just PR
Sept 12–13, 2026: drivers in Hanoi, Ho Chi Minh City and Da Nang organized a two-day app log-off, coordinated through a 166,000-member driver community group. Multiple outlets (VnExpress, Bloomberg, AsiaNews) report commission deductions in the 30–50% range, above Grab’s stated 20–27%; exact per-ride figures vary by source and are disputed. Documented prior rounds: January 2018 (commission 20%→23.6%) and December 2020 — this is at least the third cycle of the same dispute.
The evaluation-principle reading
- 2025 is the exact year the 7 evaluation principles’ first item — increasing value for the business — finally succeeded (slide 20)
- The same filings show no comparable discipline applied to relevance to context: the course’s own principle meant to weigh local stakeholder impact
The transferable lesson
- An IMS optimized on one evaluation principle while ignoring another doesn’t fail quietly — it produces exactly this kind of headline
- “Role of innovation management” therefore includes knowing which principle a firm is currently skipping, not just which one it’s winning on
Chosen product: QR code payments in Vietnam
"QR payments" is not one app — it’s several, made to interoperate
NAPAS / VietQR
Vietnam’s national payment switch. Doesn’t hold consumer accounts itself — it’s the plumbing that makes a code generated by one bank scannable by any other bank or wallet.
MoMo
The most widely cited wallet brand (reported user counts vary by source, roughly 31–50M). Runs its own QR, cashback and vendor-onboarding programs on top of the shared standard.
ZaloPay & other wallets
Built on Zalo’s existing messaging user base — the same "already-installed app" advantage Grab’s super-app strategy used, from Exercise 1.
Bank apps
Most Vietnamese still hold their money in a bank account first. VietQR is what lets a bank app scan the exact same code as MoMo or ZaloPay, instead of needing its own closed network.
Chosen product: QR payments. Raw ideas, compatibility & complexity.
Rule for this step: quantity over quality. 20 ideas, each tagged with the attribute it attacks, and marked ✅ already live in the market today or 💡 a new idea the group is proposing. First 10:
- ✅ One single national QR standard (VietQR) instead of a different code per bank/wallet compatibility
- 💡 Offline/low-data fallback mode for weak-signal areas compatibility
- ✅ Static printed QR glued to the xe ôm helmet or taxi dash — scan-only, no app pairing, works even on a near-dead phone compatibility
- 💡 USSD-style QR confirmation (*101#-type menu) for feature phones, no smartphone or data plan required compatibility
- ✅ ASEAN QR interoperability so a Vietnamese tourist in Bangkok, or a visitor here, scans with their own home app compatibility
- 💡 Voice-guided scan flow for elderly or low-literacy users complexity
- ✅ Bigger on-screen confirmation + sound cue, so the payer visibly sees it went through complexity
- 💡 One-tap "repeat last payment" for regulars — same xé ôm driver, same bánh mì stall, every morning complexity
- ✅ Face-unlock to confirm a payment instead of typing a PIN — one fewer step at the register complexity
- ✅ Cashback or lucky-draw for a user’s first 10 QR payments trialability
Chosen product: QR payments. Raw ideas, trialability, observability & advantage.
The remaining 10 ideas — same legend: ✅ already live, 💡 new idea.
- ✅ Market/street-vendor onboarding kiosks, free QR sticker printed on the spot trialability
- 💡 Zero-fee "QR Tết" campaign during Lunar New Year, timed to a cash-heavy ritual (lì xì envelopes) trialability
- 💡 University canteen goes QR-only one day a week — students form the habit, then teach it to parents at home trialability
- ✅ "Paid by QR" badge displayed at the stall, visible to the next customer in line observability
- 💡 Published real-time national adoption counter (“X million payments today”) observability
- 💡 Public map/leaderboard of which wet markets have gone fully QR — social proof, and a little peer pressure on the ones that haven’t observability
- ✅ No-fee guarantee for small transactions under a set amount rel. advantage
- 💡 Instant refund flow for failed/duplicate scans, no waiting on hold rel. advantage
- 💡 Loyalty points that stack across banks/wallets via VietQR, instead of a separate point balance locked inside each app rel. advantage
- 💡 Chargeback-style buyer protection on QR transfers, which today are treated as irreversible — closing the trust gap with card payments rel. advantage
All 20 ideas, compared in one table
9 of 20 are already live somewhere in the market — the group's real job is spotting the 11 genuine gaps, not reinventing what VietQR, MoMo or the banks already ship.
| Idea | Attr. | St. | Already done by |
|---|---|---|---|
| National QR standard (VietQR) | Compat. | ✅ | NAPAS, since 2021 |
| Static printed QR on helmet/dash | Compat. | ✅ | street vendors, xe ôm, today |
| ASEAN QR interoperability | Compat. | ✅ | piloted, VN–Thailand/Cambodia |
| Offline/low-data fallback | Compat. | 💡 | — |
| USSD QR for feature phones | Compat. | 💡 | — |
| Bigger confirmation + sound | Complex. | ✅ | most bank/wallet apps |
| Face-unlock to confirm | Complex. | ✅ | standard biometric option |
| Voice-guided scan flow | Complex. | 💡 | — |
| One-tap repeat payment | Complex. | 💡 | partial, saved-merchant lists |
| Cashback, first 10 payments | Trial. | ✅ | MoMo, ZaloPay, banks |
| Idea | Attr. | St. | Already done by |
|---|---|---|---|
| Vendor onboarding kiosks | Trial. | ✅ | MoMo/VNPay market drives |
| Zero-fee “QR Tết” campaign | Trial. | 💡 | — |
| University QR-only canteen day | Trial. | 💡 | — |
| “Paid by QR” badge at stall | Observ. | ✅ | ubiquitous stickers today |
| National adoption counter | Observ. | 💡 | — |
| Public QR-market leaderboard | Observ. | 💡 | — |
| No-fee small transactions | Advant. | ✅ | VietQR P2P, typically free |
| Instant refund, failed scans | Advant. | 💡 | dispute exists, not instant |
| Loyalty points stack across apps | Advant. | 💡 | —, fragmented today |
| Chargeback-style protection | Advant. | 💡 | largely absent today |
Why these 2 beat the other 18
Filter rule: attack the weakest attribute first. The scorecard shows complexity and observability already strong — the real gap is trust (relative advantage) and reach into the remaining ~30% cash users (compatibility).
| Attribute | Score (VietQR, 2025) |
|---|---|
| Relative advantage | Medium — fast and free for most, but failed/duplicate scans erode trust fast |
| Compatibility | Medium — ~30% of transactions are still cash, concentrated among older or rural users |
| Complexity | Low — scan and confirm, already simple |
| Trialability | High — nearly free to try once |
| Observability | High — ~2.1M outlets already display a QR code |
Directly repairs relative advantage, the real soft spot — one bad scan with no clear fix is what pushes a hesitant user straight back to cash.
Attacks compatibility exactly where the remaining 30% lives — informal vendors, not banked urban shoppers who already converted.
Dvorak vs. QWERTY: the “better” keyboard that never won
August Dvorak patented his layout in 1936, redesigning it around letter frequency to reduce finger travel. The famous 1944 Navy study, run by Dvorak himself, claimed Dvorak typists became 74% faster and 68% more accurate. It is now considered unreliable — the 1956 GSA-commissioned Strong study, run with proper controls, found retrained Dvorak typists only matched their old QWERTY speed. They never beat it.
Two separate failures, stacked on top of each other
Failure 1: the proof itself was flawed
- Dvorak was the Navy’s own top expert in time-and-motion studies — he analyzed his own invention’s results, a textbook conflict of interest
- Liebowitz & Margolis (1990) found the Dvorak and QWERTY test groups were not equally skilled to begin with
- 1950s–1970s follow-up research consistently found little or no real advantage
Failure 2: switching cost, even if it had been better
- Touch-typing is procedural memory — millions of trained typists, retraining is slow and risky mid-career
- Every keyboard, keycap mold and typing-class curriculum was already built for QWERTY — a network effect, not a technology gap
- This is compatibility failing for a totally different reason than EVs: not missing infrastructure, but locked-in human skill
Why Dvorak never diffused: the full reflection
The first problem was the evidence itself. The best-known proof, a 1944 US Navy study, was designed and run by Dvorak — the Navy’s own leading expert in time-and-motion analysis — and reported startling gains: 74% faster typing, 68% fewer errors. Economists Liebowitz and Margolis later showed the test groups were not comparably skilled to begin with. When the US government’s General Services Administration ran an independently controlled follow-up in 1956, retrained Dvorak typists only matched their prior QWERTY speed. They never exceeded it.
The second problem was compatibility, structural in a different way than usual: touch-typing is procedural memory, built into the hands of millions of typists over years of training. Retraining was slow, risky to a working typist’s income, and every keyboard, typewriter mold, and school curriculum already assumed QWERTY. That installed base, not a conspiracy, is what economists call a network effect.
The lesson generalizes beyond keyboards: sometimes a challenger fails to diffuse not because the incumbent closes a gap, but because the evidence for the challenger’s advantage was never as solid as its proponents believed — and even a real advantage can lose to the sheer cost of relearning a skill millions of people already have.
"VNeID: Vietnam’s National Digital Identity"
Problem statement: paper ID cards and in-person, agency-by-agency paperwork mean queues, duplicate data entry, and real fraud risk — and the pandemic needed a trusted digital credential immediately, not eventually. Why now: by mid-2025, over 62 million citizen accounts were already issued, with daily logins up to four times 2023 levels — this is no longer an optional app, it’s becoming mandatory infrastructure.
Diffusion forced sector by sector, by decree
Type, level, and who’s required to use it
2. Overview
Type: Paradigm innovation (replaces the citizen–government relationship itself: one verified digital identity instead of a paper card plus a separate login per agency) combined with Process innovation (procedures move online).
Level: Disruptive to a century-old paper-ID and in-person dossier system; rollout is incremental, sector by sector.
Two tiers: Level 1 (self-service in-app, limited features) vs. Level 2 (one in-person visit for biometric capture at a police station — still required for most mandatory services, the one friction point the mandate itself can’t remove).
2025–26, in numbers
- Over 62M citizen accounts + 292M+ organization accounts (mid-2025); daily logins 3–6M, up to 4× 2023
- PM Directive 24 (Sep 2025): 25 full-process public services moved onto VNeID; paper copies dropped for them from Oct 2025
- 12 essential document types integrated per Resolution 66.22/NQ-CP; the 5 required for fee relief: birth certificate, bank/payment account, social-security account, phone number, e-health book
- Fee relief from Aug 2026: 34 procedures 100% free, 8 high-value transactions cut 10–50%, for citizens with 5 core documents linked
Value proposition and SWOT
3–4. Core analysis, impact & SWOT
Value proposition: one verified identity, reusable across every agency and, increasingly, banks and platforms — fewer queues for citizens, less duplicate fraud-prone paperwork for the state.
- S: quantified, not just adoption — by Sept 2026, 768,000 eligibility look-ups and 14,700+ fee-free dossiers saved citizens ≈232.6M VND directly
- W: an account can be locked if its linked phone number isn’t registered in the citizen’s own name (Decree 320) — a mandate with a real lockout edge
- O: a signed plan to link VNeID with Singapore’s and Laos’ ID systems, expanding across ASEAN — the "super app" ambition, moving
- T: fake-VNeID phishing apps are real — one Đà Nẵng victim lost 129M VND (Jul 2025); police run a single verified hotline, 1900.0368, precisely because trust in the brand is now worth exploiting
5. Conclusion
Summary: VNeID doesn’t win adoption attribute by attribute like every other example in this deck — it uses regulation to force compatibility directly, sector by sector.
Key lesson, stated as a rule: when a firm or state controls the channel citizens must use anyway (banking rails, e-government portals), diffusion can be legislated, not earned — but that shortcut borrows against public trust, and the bill comes due at the first major failure or breach.
Diffusion is not automatic — it has to be managed
Technological excellence alone does not guarantee success; commercial victory relies on market adoption. Managers must actively design products and strategies for each adopter segment, not assume the S-curve will climb itself.